
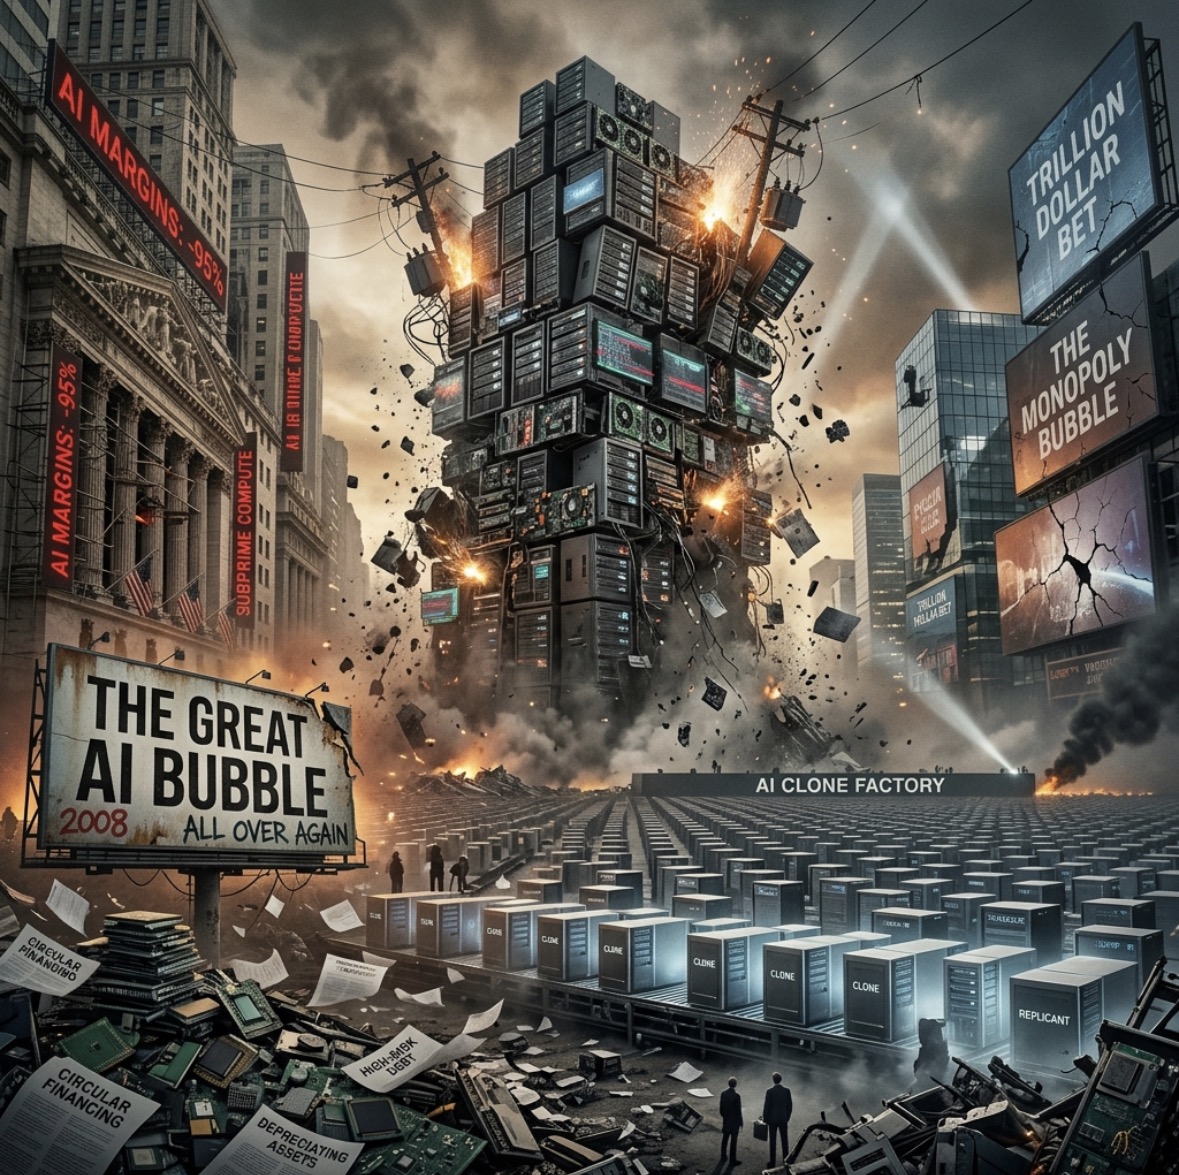
The Clone Trap: Why the Multi-Trillion-Dollar AI Buildout Looks Like 2008 All Over Again
For the past three years, Wall Street and Silicon Valley have operated under a single, intoxicating premise: whoever builds the largest artificial intelligence model will effectively own the future of the global economy. On the back of that thesis, tech giants, venture capitalists, and credit markets have committed well over a trillion dollars to data centers, specialized microchips, and power grid expansions.
Yet beneath the staggering capital expenditure lies a fundamental math problem that looks less like the dawn of a monopolistic software empire and far more like the structural buildup to the 2008 housing crash. The core assumption driving these valuations—that a handful of companies will secure an unassailable moat and charge monopoly rents on human productivity—is already breaking down in real time.
Instead of a winner-take-all market, the AI industry has engineered the most expensive clone factory in corporate history.
The Convergence Problem and the Zero-Moat Reality
In previous technology cycles, dominant players survived massive infrastructure bubbles because they held structural monopolies. Amazon built physical logistics and fulfillment networks; Google had an unreplicable index of the web and an entrenched ad exchange; Apple had a locked-down hardware ecosystem.
Large language models have none of these protections. At their core, the flagship models from OpenAI, Google, Anthropic, and Meta are all trained on the exact same finite resource: the public internet, digitized books, and scraped human text. Because they are fed the same diet and rely on the same underlying transformer architecture, their capabilities are converging rapidly.
Whenever a frontier lab spends billions of dollars and six months of compute to achieve a breakthrough in reasoning or coding, competitors—alongside open-weight models released for free by companies like Meta or DeepSeek—replicate that capability within a matter of weeks, often at a fraction of the training cost.
This creates a brutal economic inversion. The cost to produce a frontier model is astronomical, as every major lab bids against the same bottlenecks of Nvidia GPUs, high-bandwidth memory, and electrical capacity. Meanwhile, for the end customer, switching costs are virtually zero. In traditional enterprise software, ripping out an old database takes years. In generative AI, switching from one provider to a cheaper clone requires a developer to change two lines of API code.
Basic microeconomics dictates what happens when production costs skyrocket, products become indistinguishable, and switching costs drop to zero: profit margins collapse toward the cost of electricity. You cannot extract monopoly profits from a commodity, and intelligence has been commoditized at record speed.
The Circular Revenue Illusion
If the underlying software is rapidly becoming a low-margin utility, how are tech valuations continuing to defy gravity? The answer lies in a closed loop of vendor financing and circular accounting that echoes the telecom bubble of 2000 and the mortgage machinery of 2007.
Currently, a massive share of the revenue growth reported by big tech comes from passing the same capital back and forth within a remarkably tight circle. A cloud hyperscaler like Microsoft or Amazon invests billions of dollars into an AI lab. That startup immediately turns around and spends the vast majority of that investment renting cloud servers from the very company that funded them. The hyperscaler books those server rentals as explosive "AI cloud growth," uses that revenue to justify buying tens of billions of dollars in chips from Nvidia, and Nvidia in turn invests capital back into the AI ecosystem—including heavily leveraged specialist cloud providers—to keep chip orders flowing.
At the top of the funnel, it looks like historic, vertical demand. At the bottom of the funnel, actual net-new revenue from outside consumers and non-tech enterprises remains a fraction of what is required to pay off the hardware before those chips depreciate into obsolescence in three to four years.
Institutional analysts at firms like Goldman Sachs and the Yale School of Management have repeatedly pointed out this "trillion-dollar gap": there is still no consumer or enterprise application generating anywhere near the free cash flow required to justify the physical buildout.
Why This Rhymes With the 2008 Housing Crash
Comparing AI to the subprime mortgage crisis might sound extreme, given that Big Tech has far stronger balance sheets than 2007 homebuyers. However, as economists at the Center for Economic and Policy Research (CEPR) have noted, the systemic threat isn't the technology itself—it is the concentration of market wealth built on a flawed collateral assumption.
In 2006, the entire financial apparatus operated on the belief that U.S. housing prices could never fall nationwide. Because everyone believed the collateral was invincible, trillions of dollars in debt and complex derivatives were stacked on top of mortgages that the underlying borrowers could never realistically pay back through their wages.
Today, the stock market's record highs—and by extension, the retirement accounts and 401(k)s of millions of everyday people—are propped up almost entirely by five or six companies making a single, correlated bet on AI infrastructure. Worse, because the scale of data center construction has exceeded even Big Tech's cash reserves, the buildout is increasingly being funded by private credit markets, corporate bond issuances, and utilities taking on massive debt backed by pension funds.
The chips themselves have even become the literal collateral for billions of dollars in debt held by secondary cloud providers. Just like housing in 2007, the debt is real, the physical construction is real, and the cash flows meant to pay for it all are entirely theoretical.
The Inevitable Unwind
To be clear, bursting bubbles do not mean the underlying asset is useless. Houses did not disappear in 2008, and the fiber-optic cables laid down before the 2000 dot-com crash eventually powered the modern internet. Generative AI is a genuine technological leap that will remain permanently embedded in how we write code, process data, and automate routine work.
The crisis arrives when corporate boards and institutional lenders finally admit that a useful tool is not the same thing as a monopolistic goldmine.
When the realization hits that no single AI company is going to conquer the market, that they have instead spent sovereign level wealth to enter a brutal price war against twenty identical clones—capital expenditure will freeze. Once Microsoft, Google, or Meta blinks and trims its server budgets by even twenty percent, the circular revenue loop runs in reverse. Chip orders evaporate, the secondary debt markets financing the data centers seize up, and the handful of mega-cap stocks holding up the entire S&P 500 face a violent repricing.
There is no single AI monopoly coming to capture the world's wealth. What we have instead is a historic overbuild of identical technology, propped up by circular financing, waiting for the moment Wall Street remembers how to do basic math.